The Silent Budget Buster: Your Supermarket Cart
Next to housing, food is consistently the largest expense for households worldwide. But unlike your rent or mortgage, which is fixed each month, your grocery bill is 100% variable and within your control.
A family that spends $1,200 a month on groceries and takeout can often trim that down to $650–$750 with a few deliberate supermarket strategies. That is an extra $400 to $550 in pure cash savings every month that can go directly into your emergency fund or investment portfolio.
Here are 15 practical, battle-tested grocery hacks to slash your grocery receipts without living on plain instant noodles.
1. Shop Your Pantry Before Writing Your List
The most expensive food is the food you throw away. Before opening your notes app or writing a grocery list, inspect your refrigerator, freezer, and pantry. Plan at least three dinners around ingredients you already own (that can of crushed tomatoes, dried lentils, or frozen chicken breasts).
2. Never Step Foot in the Aisle Hungry
This sounds cliché, but the biological reality is undeniable: shopping while hungry compromises your prefrontal cortex. A 2013 Cornell study found that hungry shoppers purchased 31% more high-calorie and impulse snack items than those who ate before shopping. Drink a large glass of water and eat a light protein snack before leaving the house.
3. The "Unit Price" Eye Scan
Supermarkets deliberately package items in deceiving sizes to disguise price increases (shrinkflation). Always ignore the bold sale price and look at the tiny print in the corner of the shelf tag: the unit price (cost per ounce, gram, or liter). Often, the "value pack" is actually more expensive per gram than two smaller standard boxes on sale.
4. Look High and Low (The Eye-Level Trap)
Big brand food conglomerates pay supermarkets premium "slotting fees" to place their high-margin, expensive products directly at adult eye level (between 4 and 5.5 feet off the floor). The budget store brands, bulk grains, and value staples are routinely relegated to the bottom shelf or top rack. Always look up and down before choosing.
5. Embrace the "Two Meatless Days" Rule
Meat is frequently the single most expensive line item on a grocery receipt. You don't have to become a strict vegan to reap massive financial benefits:
- Swap ground beef for black beans or lentils in chili and tacos.
- Make hearty chickpea curry or vegetable stir-fries with tofu twice a week. Dropping just two meat-heavy dinners per week can save an average household $30 to $50 per week ($120–$200/month).
6. Switch to Frozen Vegetables and Berries
Fresh berries and produce often spoil within 4 days in the crisper drawer. Frozen vegetables and fruits are flash-frozen at peak ripeness, preserving the same vitamin density at 40% to 60% lower cost — and zero waste. Use frozen spinach and broccoli for cooked dishes and frozen berries for breakfast oats.
7. Beware of Pre-Cut Convenience Fees
Supermarkets charge an exorbitant markup for convenience:
- Pre-cut watermelon or pineapple cubes can cost 300% to 400% more per pound than buying the whole melon.
- Grated cheese includes potato starch anti-caking agents and costs up to 40% more than a block of cheddar you can shred in 30 seconds.
8. Master the "Inverse Meal Planning" Method
Most people choose recipes online first, then shop for ingredients regardless of price. Flip the formula:
- Open the supermarket's weekly digital circular/flyer.
- See which produce and protein are marked down 30% to 50% that week.
- Build your 5 weekly dinners around those discounted sale items.
9. Buy Store Brands (They Are Often Made in the Same Facility)
Generic store brands (Kirkland, Great Value, Woolworths Essentials, Trader Joe's) are frequently manufactured by the exact same name-brand factories under private white-label agreements. In taste tests, staple items like flour, oats, salt, canned beans, and milk are completely indistinguishable from national brands, while costing 25% to 35% less.
10. Stick to the Perimeter of the Store
The healthiest and most cost-effective whole foods live along the perimeter walls: fresh produce, refrigerated dairy, eggs, and butcher counters. The inner aisles are heavily populated with processed snack foods, sodas, and packaged meals designed for high corporate profit margins.
11. Practice the "Rule of Substitution"
If a recipe calls for an obscure $9 spice or specialty sauce you will only use once, do not buy it. Use a common substitute you already possess (e.g., lemon juice instead of rice vinegar, dried herbs instead of fresh, plain yogurt instead of sour cream).
12. Utilize Store Pickup or Click-and-Collect
If you struggle with supermarket impulse buys, order online for free curbside pickup. Online ordering provides two massive advantages:
- You see your running cart total update in real-time before clicking "Place Order".
- You eliminate aisle-wandering temptations and end-cap snack displays entirely.
13. Revisit the "Cash Envelope" System
If digital card spending feels too abstract, test withdrawing your exact grocery allocation in physical cash for 30 days. When you go into the store with a crisp $100 bill in an envelope, you are physically forced to stay under budget.
14. Regrow Green Onions and Celery
Do not throw away the root bottoms of scallions/green onions or celery. Place the root base in a small cup of clean water on your windowsill. In 5 to 7 days, crisp new stalks will sprout. You can harvest fresh green onions 3 to 4 times from a single purchased bunch!
15. Track Your Grocery Baseline
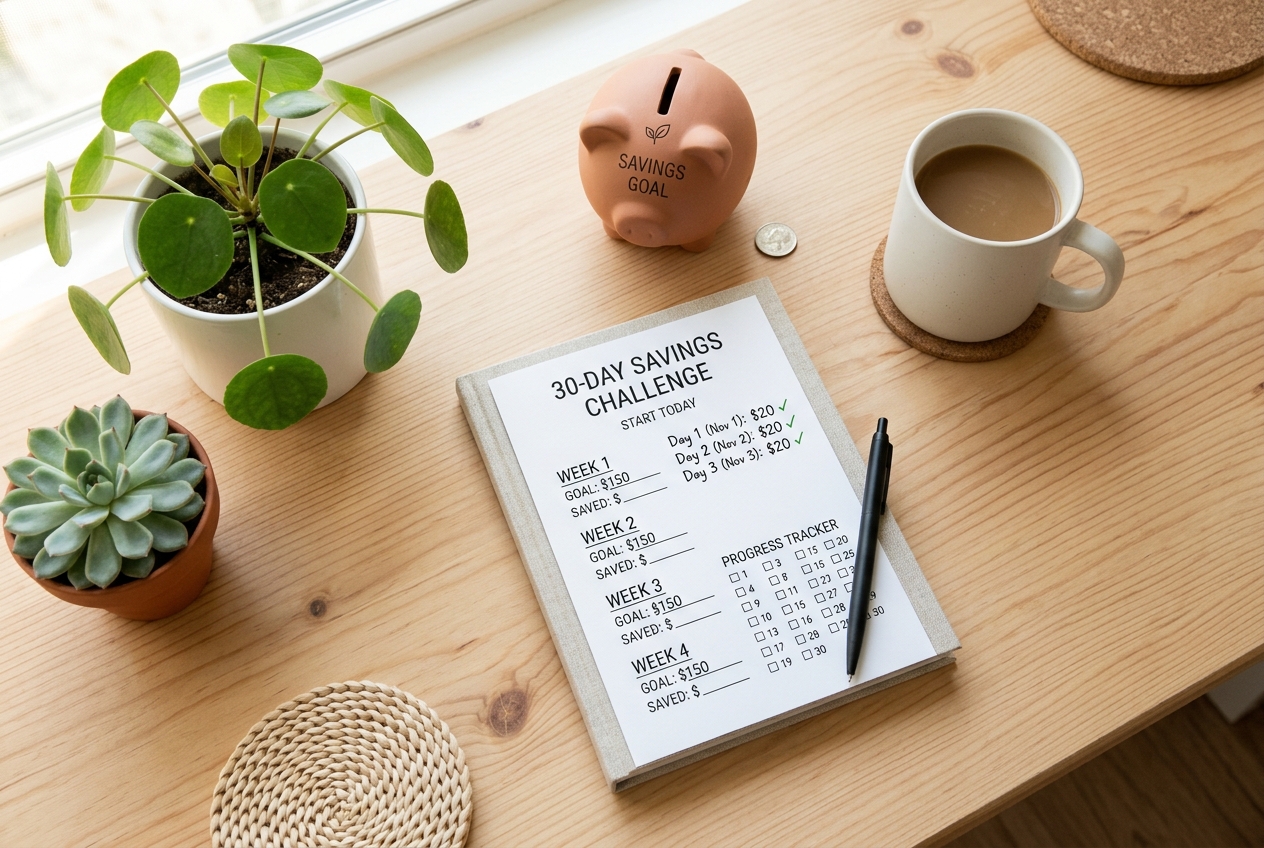
You cannot improve what you do not measure. Use our free printable 30-Day Mindful Spending Tracker to note down each grocery run and observe where impulse splurges sneak into your routine.
The Compound Impact
Saving $75 a week on groceries doesn't feel like a life-altering sum in the moment. But over the course of a single year, that represents $3,900 in cold hard cash.
If you invest that $3,900 in a balanced low-cost index fund or stash it in a 5.0% High-Yield Savings Account, compound interest takes over. Use our interactive Compound Interest & Savings Calculator to see how an extra $300 a month turns into tens of thousands of dollars over time.